
Crude oil tanker operator DHT Holdings (NYSE:DHT) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 319% year on year to $332.4 million. Its GAAP profit of $1.68 per share was 12.9% above analysts’ consensus estimates.
For more on DHT Holdings, read our full research report, available free.
DHT Holdings (DHT) Q3 2026 highlights:
- Revenue $332.4 million vs S&P analysts' consensus estimates of $254.3 million (319% year-on-year growth, 30.7% beat)
- EPS (GAAP) $1.68 vs analysts' consensus estimates of $1.49 (12.9% beat)
- Adjusted EBITDA $269.5 million vs analysts' consensus estimates of $209.6 million (81.1% margin, 28.6% beat)
- Operating margin 82.7%, up from 59.8% in the same quarter last year
- Market capitalization $3.33 billion
Revenue growth
Cyclical industries such as energy can make mediocre companies look good for a time, but a long-term view reveals which businesses can withstand and adapt to changing conditions. DHT Holdings’s 30.1% annualized revenue growth over the last five years was strong. Its growth beat the average energy upstream and integrated energy company and shows its offerings resonate with customers.
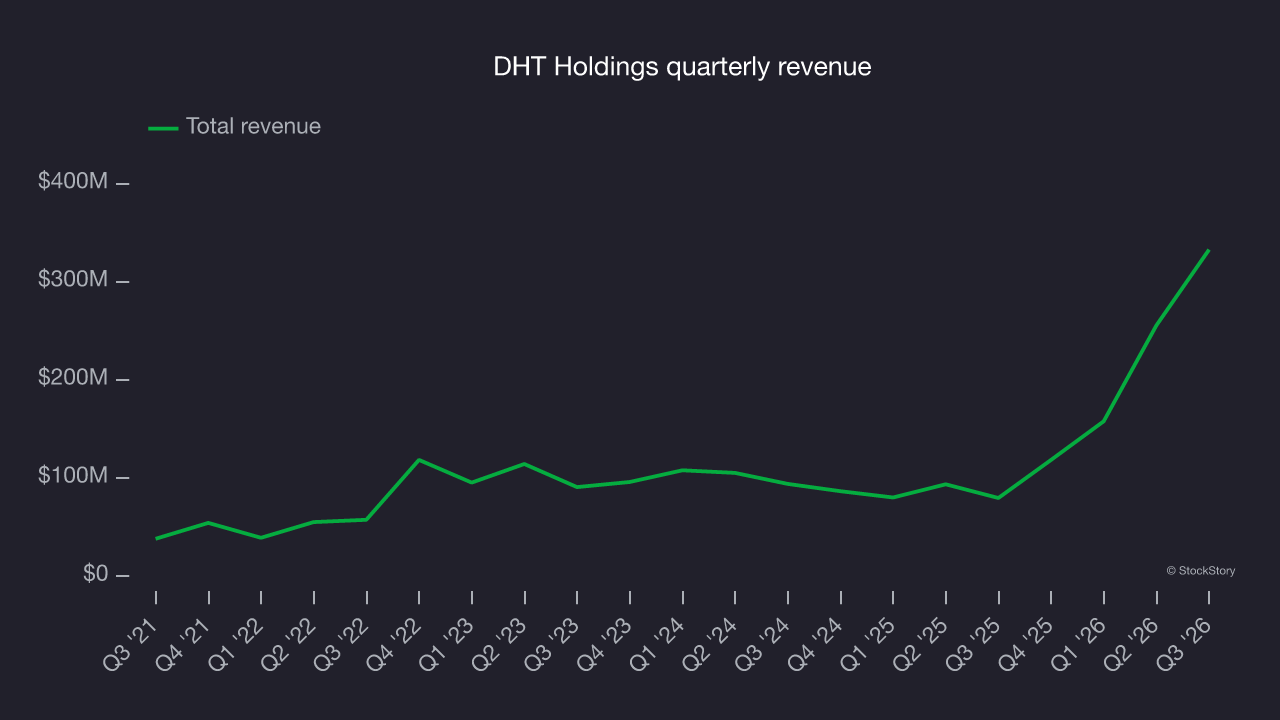
Within energy, a single time frame, even a long one, only sheds light on how well a company rode the last commodity cycle. To better assess whether a company compounds through cycles, it helps to take an even longer, ten-year view. DHT Holdings’s annualized revenue growth of 11% over the last ten years is below its five-year trend, but the results still suggest decent demand.
This quarter, DHT Holdings reported year-on-year revenue growth of 319%, and its $332.4 million of revenue beat Wall Street’s consensus estimates by 30.7%.
Adjusted EBITDA margin
Adjusted EBITDA margin strips out accounting distortions tied to depletion and historical drilling spend, providing a clearer view of the cash-generating power of the underlying asset base before financing and reinvestment decisions.
DHT Holdings has performed well over the last five years. It demonstrated high profitability for an upstream and integrated energy business, with an average EBITDA margin of 77.3%.
Looking at the trend in its profitability, DHT Holdings’s EBITDA margin rose by 28.5 percentage points over the last year, as its revenue growth provided operating leverage.
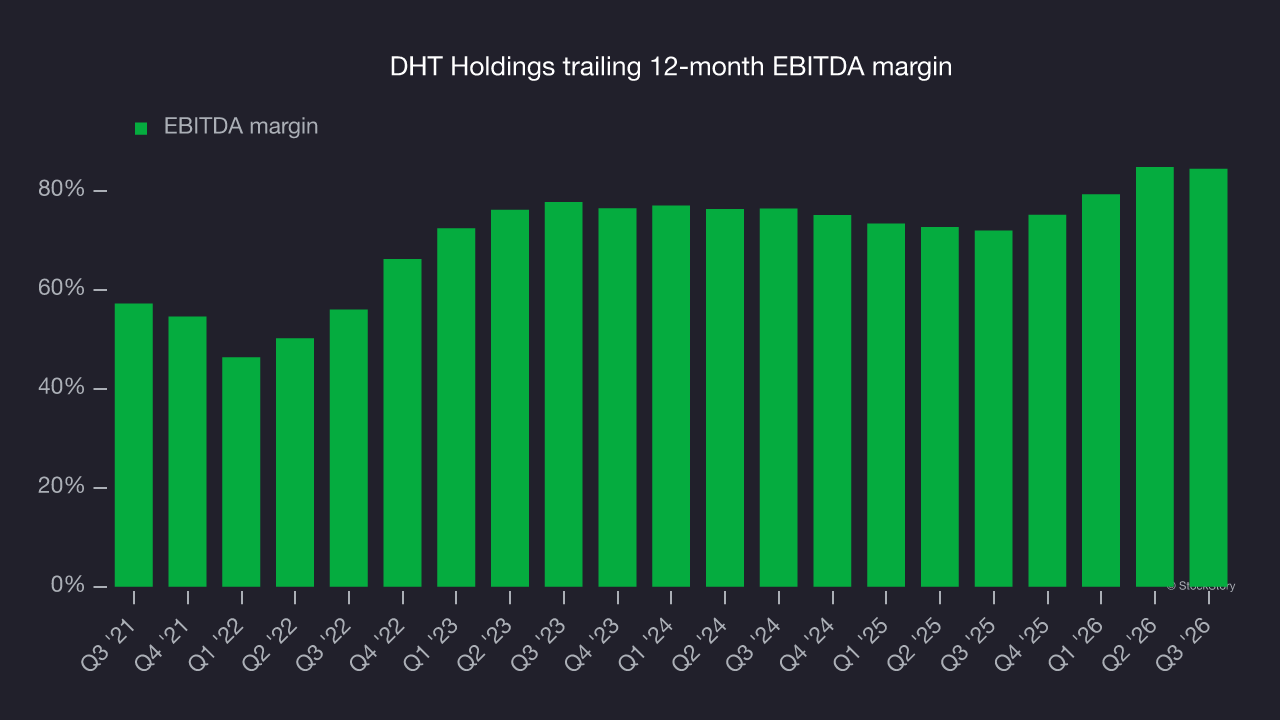
This quarter, DHT Holdings generated an EBITDA profit margin of 81.1%, up 8.3 percentage points year on year. The increase was a positive sign, showing improved efficiency. Adjusted EBITDA beat Wall Street’s consensus estimates by 28.6%.
Key takeaways from DHT Holdings’s Q3 results
DHT Holdings delivered a solid quarter, with both EBITDA and revenue beating analysts’ consensus estimates by wide margins. Shares edged higher 1.8% to $20.93 immediately after the release.
DHT Holdings reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. That decision calls for considering its valuation and business quality, as well as what happened in the latest quarter. For more, read the full research report here (it’s free).